Businesses of all sizes often grapple with the challenge of funding inventory without straining cash flow. Inventory financing provides a lifeline by allowing companies to use their stock as collateral for loans or lines of credit.
This guide illuminates the nuts and bolts of this financial tool, outlining the best options available and how they can bolster your business operations. Discover how to manage your inventory management system, keep your shelves stocked and sales humming; read on for insights that can transform your business line and approach to inventory funding.
Key Takeaways
Inventory financing enables companies to borrow money against the value of their stock, providing a flexible way to fund inventory without affecting cash flow.
There are different types of inventory financing available, including inventory loans, lines of credit and term loans – each with its own advantages and terms tailored to various business needs.
The process for obtaining inventory financing involves comparing lenders’ rates, evaluating funding times and repayment terms, plus gathering necessary documents like tax returns and financial statements for application.
Alongside traditional options like bank loans or SBA 7(a) programs, alternative solutions such as invoice factoring, merchant cash advances and purchase order financing can also support businesses in managing finances more effectively.
Vendor financing presents itself as an advantageous option particularly for start-ups or businesses facing credit challenges by allowing them access to essential capital using their future inventory.
Understanding Inventory Financing

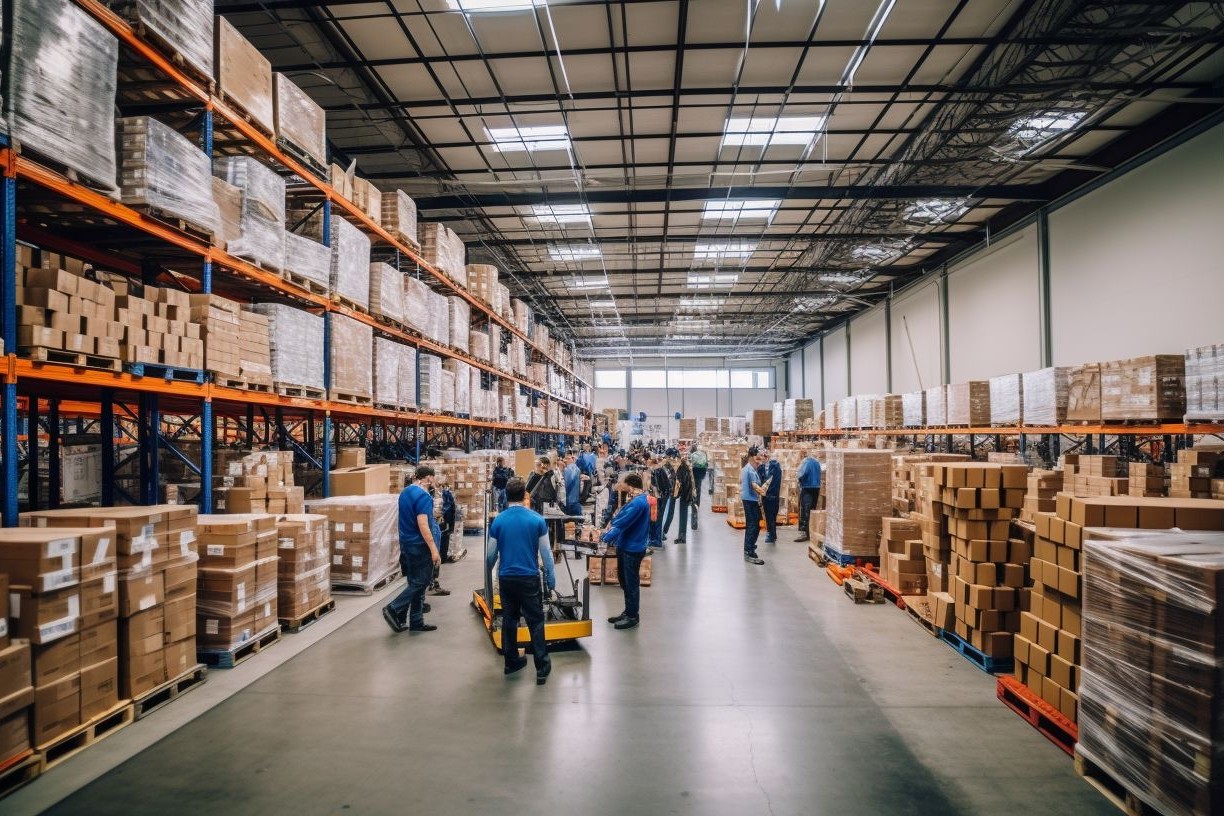
Inventory financing offers a lifeline to small and medium-sized enterprises looking to boost their stock without tying up other assets. This financial option allows companies to borrow against the value of items they plan to sell.
Retailers, wholesalers, and distributors often utilise this type of lending during periods when cash flow might be inconsistent. The inventory itself serves as collateral until the loan is repaid, affording businesses a degree of flexibility that may not be possible with traditional loans secured by fixed assets.
Seizing control over one’s supply chain without disturbing working capital becomes simpler with inventory finance. It caters precisely to those who need short-term funding solutions, while also helping them leverage their existing products for growth opportunities.
As directors explore this avenue, understanding the nuances can prepare them for smoother negotiations with lenders offering varying interest rates and credit terms.
How Does Inventory Financing Work?

In the realm of inventory financing, a business owner gets the capital it needs by using its stock as leverage. This type of business funding often functions on a very straightforward principle: lenders provide businesses with the money to buy products that will eventually be sold.
It’s different from traditional loans because you’re essentially borrowing against items you don’t yet own but plan to sell. The terms and amount of your loan depend on the value of your prospective inventory, assessed through due diligence by lenders.
Once an agreement is made, funds are transferred to financing company, typically as a lump sum or through a credit line that can be drawn upon as required for purchasing stock. Directors must ensure their company maintains accurate sales forecasts and inventory lists as these documents play crucial roles in securing favourable terms for financing options.
As items are sold and profits generated, repayments begin according to agreed-upon schedules and interest rates—often this means that fixed monthly payments, until the total borrowed amount plus any additional charges have been settled fully with the lender.
Types of Inventory Financing
Discover the various instruments at your disposal within inventory financing, each uniquely tailored to bolster cash flow gaps, your stock purchasing power and enhance business liquidity – delve deeper for insights on choosing the right option for your operation.
Inventory Loans
Inventory loans offer a valuable opportunity for businesses to leverage their intended purchases as collateral. Typically, these loans are taken out by companies that require stock replenishment but lack the immediate funds.
With an inventory loan, your business can secure financing against the value of future inventory, allowing you to maintain operations and meet customer demand without significant cash flow disruption.
Securing a loan on inventory is straightforward – lenders appraise the market value of your goods and extend credit accordingly. The inventory serves as security for the loan; therefore, if sales projections fall short and you’re unable to repay business loan from revenue, lenders may repossess the unsold items.
This finance option is beneficial because it provides quick access to capital with less stringent qualification criteria than traditional bank loans, making it accessible even to newer businesses with promising sales trajectories.
Inventory Lines of Credit
Inventory lines of credit offer a flexible financing solution for businesses looking to manage their stock levels effectively. Companies can draw from these lines as needed, purchasing or producing inventory without depleting cash reserves.
The inventory of small business loans acquired acts as collateral, which means less risk for the small business loan owner compared to options requiring personal assets.
Securing an inventory line of credit typically depends on the value of your existing inventory and your company’s financial health. It allows you to only pay interest on the amount you actually use, making it a smart option for companies with fluctuating inventory needs.
This type business line of credit provides breathing room for financial planning, giving directors the ability to address immediate stock requirements while preserving capital for other strategic activities.
Term Loans
Moving beyond the flexible nature of inventory lines of credit, term loans present a more structured financing option for directors looking loan funding to secure their inventory needs. These loans are typically disbursed as a lump sum by lenders with predetermined repayment terms.
They offer predictable payment schedules which can be crucial in budgeting and financial planning.
Directors should note that obtaining these term loans requires meeting certain qualifications; minimum credit scores, business revenue benchmarks, and operational time frames are standard prerequisites.
Online lenders might facilitate fast access to funds with less paperwork involved than traditional banks. To apply for a short term loan an online lender successfully involves gathering comprehensive business financials – balance sheets and profit & loss statements included – ensuring directors have all necessary documents at hand to streamline the application process.
The Pros and Cons of Inventory Financing

Determining whether inventory financing aligns with your business needs hinges on a nuanced understanding of its advantages and potential drawbacks. As such, directors must weigh the increased liquidity and growth opportunities against possible high costs and stringent borrowing conditions to make an informed decision.
Pros of Inventory Financing
Inventory financing offers an ingenious solution for businesses needing to stock up on products without crippling their cash flow. As a self-collateralising option, this form of lending uses the inventory itself as collateral, creating a safety net for both the lender and borrower.
Companies benefit from unlocking capital tied up in unsold goods, which can then be reinvested to fuel growth and sales volume. Directors will find this particularly useful when planning ahead for peak seasons or considering expansion with new product lines.
The straightforward application process means that access to funds can often be quicker compared to other financial products. This is a boon for small to medium-sized enterprises (SMEs) looking at leveraging their inventory on credit while avoiding the slower turnaround times typical of traditional bank financing.
With loan amounts based on appraisal value, typically ranging between 50-70%, companies are empowered with sufficient capital to negotiate supplier discounts or prepare early for seasonal demand surges—both strategies conducive to enhancing revenue potential and competitive edge in the market.
Cons
High interest rates often burden inventory financing, hitting hard especially for those with a shaky credit history or businesses just starting. The higher costs reflect the increased risk to lenders when collateral for bank loan is tied up in unsold stock.
Also, stringent approval processes can present significant hurdles, with some companies finding it tough to meet the exacting standards required by financial institutions.
Weekly repayments might strain your cash flow further, testing even the most meticulous of inventory management plans. Personal guarantees add another layer of pressure, putting personal and other business assets on the line should business revenues falter.
For products that don’t fly off shelves easily, this type of financing becomes less viable – tying up funds in slow-moving goods could spell trouble for maintaining healthy business finances.
Steps to Obtain Inventory Financing
Securing inventory financing is a strategic move for directors looking to bolster their company’s operations with additional working capital. It involves a methodical approach where one must navigate the landscape of lenders, scrutinise terms, and present comprehensive documentation that affirms your business’s creditworthiness and operational viability.
Compare Lenders and Rates
Choosing the right lending partner is a critical step in securing the best inventory financing options for your business. Directors should assess various lenders to ensure they receive inventory financing loans the most favourable rates and terms that align with their company’s needs.
Review each lender’s maximum loan amount and see which one matches your inventory funding requirements.
Check the minimum credit score needed for eligibility.
Analyse the annual percentage rate (APR) provided by different lenders. Understand this will impact the total cost of borrowing—SBA loans may offer an estimated APR of 11.50-15.00%.
Look into any additional fees associated with obtaining a loan, such as origination fees or appraisal fees that can add to the overall expense.
Investigate how quickly you can access funds once approved.
Examine repayment terms as some loans secured by inventory might have flexible payback schedules that suit seasonal businesses better than others.
Compare if there are any prepayment penalties should you decide to settle your debt ahead of schedule and reduce interest costs over time.
Evaluate Time to Funding and Repayment Terms
Evaluating the time to funding and the repayment terms is a critical step in securing inventory financing. Directors must consider these aspects carefully to ensure they align with the company’s cash flow and financial planning.
Assess the anticipated time from application to receiving funds. Different lenders have varying processing times; some may offer quick funding, while others could take weeks.
Examine repayment schedules closely. Certain loans demand weekly repayments, which could impact your cash flow more than monthly payments.
Look into whether the lender sets a specific period within which you must repay the loan entirely. These terms are crucial for maintaining healthy finances.
Check for any personal guarantees required by some loan agreements. Ensure that directors understand these commitments and their implications on personal assets.
Investigate if there are prepayment penalties for paying off the loan early. Such fees can affect your decision if you plan to settle debts ahead of schedule.
Understand that not all types of inventory financing may be available in your state. Clarify availability with potential lenders beforehand.
Consider long – term impacts on balance sheets and future borrowing ability. Frequent borrowing might affect creditworthiness over time.
Scrutinise interest rates and fees as they vary greatly among lenders. A lower rate can significantly reduce overall costs.
Review lender agreements for any hidden fees or charges that could arise during the course of the loan term.
Gather the Required Documents
Securing inventory financing necessitates meticulous preparation and the gathering of specific documentation. This process ensures lenders have a clear picture of your small business owner’s financial health.
Begin by compiling up-to-date business and personal tax returns; these provide lenders with insight into your income and taxation history.
Pull together your most recent bank statements from both your business and personal accounts to demonstrate cash flow stability.
Prepare a detailed inventory list, showcasing what products you have, their quantities, and their value to serve as potential collateral.
Furnish the specifics of your inventory management system, which should detail how you track and control your stock effectively.
Create an up-to-date balance sheet that clearly reflects your company’s assets, liabilities, and equity positions at present.
Draft a profit and loss statement; this key financial document displays operational success over time through revenues and expenses.
Predict future sales with a well – researched sales forecast to convince lenders of your growth prospects and ability to repay the loan.
Apply
Applying for inventory financing is a critical step in securing the required funds to manage your business’s stock levels. This process involves presenting a compelling case to potential lenders about your business accounts and the viability and profitability of purchasing inventory out of your business.
Start by gathering all necessary documents that you will need to apply. These often include up-to-date financial statements, tax returns, both personal and business bank statements, and information specific to your inventory.
Assess the value of your inventory accurately because lenders will base their loan offers on this evaluation. Ensure that you can provide evidence of the inventory’s worth and your ability to sell it.
Fill out the lender – provided application form thoroughly, making sure not to leave any sections incomplete. Details matter, and omissions could delay or negatively impact your application.
Articulate clearly in your business plan or statement of operations how the extra financing will contribute towards growth. Demonstrating a strategic vision for funds usage can build lender confidence.
Provide proof of annual revenue as it reassures lenders of your ability to repay the loan; this is crucial for securing their trust and investment.
Check over each detail before submission; errors or inconsistencies might raise red flags for lenders and could result in unnecessary setbacks.
Submit your application within the timelines specified by the lender. Promptness shows professionalism and helps maintain a positive momentum towards obtaining financing.
Alternatives to Inventory Financing
For businesses seeking flexibility beyond traditional inventory loans, a range of alternative financing solutions offers various pathways to better manage cash flow and support growth.
Invoice Factoring
Invoice factoring provides a quick infusion of cash by allowing companies to sell their accounts receivable at a discount. Directors should note that this method converts outstanding invoices due within 90 days into immediate capital, which can be pivotal for maintaining operations or funding growth initiatives.
Unlike traditional loans requiring collateral, invoice factoring relies on customers’ creditworthiness, not the company’s.
This alternative financing solution offers an edge over conventional methods as it accelerates cash flow without incurring debt or diluting equity. It serves as an attractive option for businesses with robust sales ledger but limited access to bank loans or sufficient collateral.
Companies benefit from less time spent chasing payments, enabling them to focus more on strategic business activities and less on managing bank account balances.
Merchant Cash Advance
Merchant Cash Advances offer a lifeline to businesses seeking immediate funds. By using cash upfront and leveraging future credit card sales, companies receive upfront cash that can be used for a variety of purposes not limited to inventory purchase.
It’s important understanding this inventory financing loan option is distinct from traditional inventory loans; it uses your predicted credit card transactions as the collateral rather than physical goods.
The appeal of Merchant Cash Advances lies in their accessibility, especially for those with strong own business credit history and daily credit card sales, but perhaps less-than-perfect credit histories. However, directors should note these advances might carry steeper fees and demand faster repayments when compared with other types of small business financing.
Consideration is paramount before opting to apply for inventory financing from an MCA due to its potential impact on cash flow given the daily or weekly deductions from sales meant to pay back the advance.
Purchase Order Financing
Moving from the cash advances discussed earlier, Purchase Order Financing offers an alternative route for companies looking to secure their inventory without immediate cash outlay.
This form of inventory financing works and becomes particularly useful when a business lands a large order but lacks the capital to purchase the necessary inventory. Rather than missing out on these potentially lucrative deals, directors can leverage Purchase Order Financing to pay suppliers directly, less business expenses and allowing operations to continue smoothly.
This tool is not just about keeping the lights on; it’s also smart strategy in action. By accessing funds through Purchase Order Financing, businesses can take advantage of supplier discounts or gear up for seasonal spikes in demand.
It paves the way for product launches and expansion that might otherwise be delayed due to funding constraints. In essence, directors gain a powerful mechanism for growth management and can handle larger orders with confidence even before any money hits their bank accounts.
Vendor Financing
Vendor financing emerges as a flexible solution for businesses eyeing inventory acquisition without the immediate funds. Companies like Fundbox cater to startup ventures, extending up to $150,000 in loans that strategically utilise the inventory itself as collateral.
This approach allows firms to maintain cash flow while securing the necessary stock to fuel operations and drive sales.
Credibly stands out by offering vendor financing options even to small businesses grappling with credit challenges, permitting access to substantial capital of up to $400,000. Such financial instruments empower companies with poor credit histories by providing them an opportunity for growth despite their past fiscal struggles.
Providing this crucial support fosters resilience and expansion in competitive markets where access to resources can dictate business longevity.
Conclusion
In exploring the landscape of inventory financing options, businesses now have a roadmap to navigate their funding options. Directors can confidently assess various loan types and select the right fit for their company’s needs.
Armed with knowledge on interest rates, lender qualifications, and repayment terms, making an informed decision becomes simpler. Act decisively; secure the financing that aligns with your business goals and propels growth forward.
Remember, choosing wisely could mean unlocking the potential to expand inventory and drive sales success.
FAQs
1. What exactly is inventory financing?
Inventory finance is a secured loan or line of credit that businesses use to purchase inventory, where the merchandise itself serves as collateral.
2. How do businesses pay back equipment and inventory loans?
Businesses must typically repay these loans on scheduled terms agreed upon with the lender, which can include banks, private lenders or through SBA 7(a) loans.
3. Can I get an inventory loan without providing any security?
No, most business inventory loans and lending options are secured loans because they require your inventory as collateral; however, there are unsecured, business loans and credit cards available too.
4. Are there different types of financing for business inventories?
Yes! Besides traditional bank loans for inventories, you can consider accounts receivable financing to finance inventory, financing, invoice financing through various lending institutions including banking facilities or private entities.
5. Does my business’s financial health affect our ability to receive inventory funding?
Absolutely. Lenders will look at your financial statements including income and cash flow statements when considering if they should provide you with a loan for your stock.
6. Are there alternatives to taking out a loan against my company’s assets for additional funds?
Indeed! Alternatives such as crowdfunding or merchant cash advances could work instead of asset-based financing like traditional debt financing with mortgage rates or interests from a credit-card or bank officer.
And there's more...